
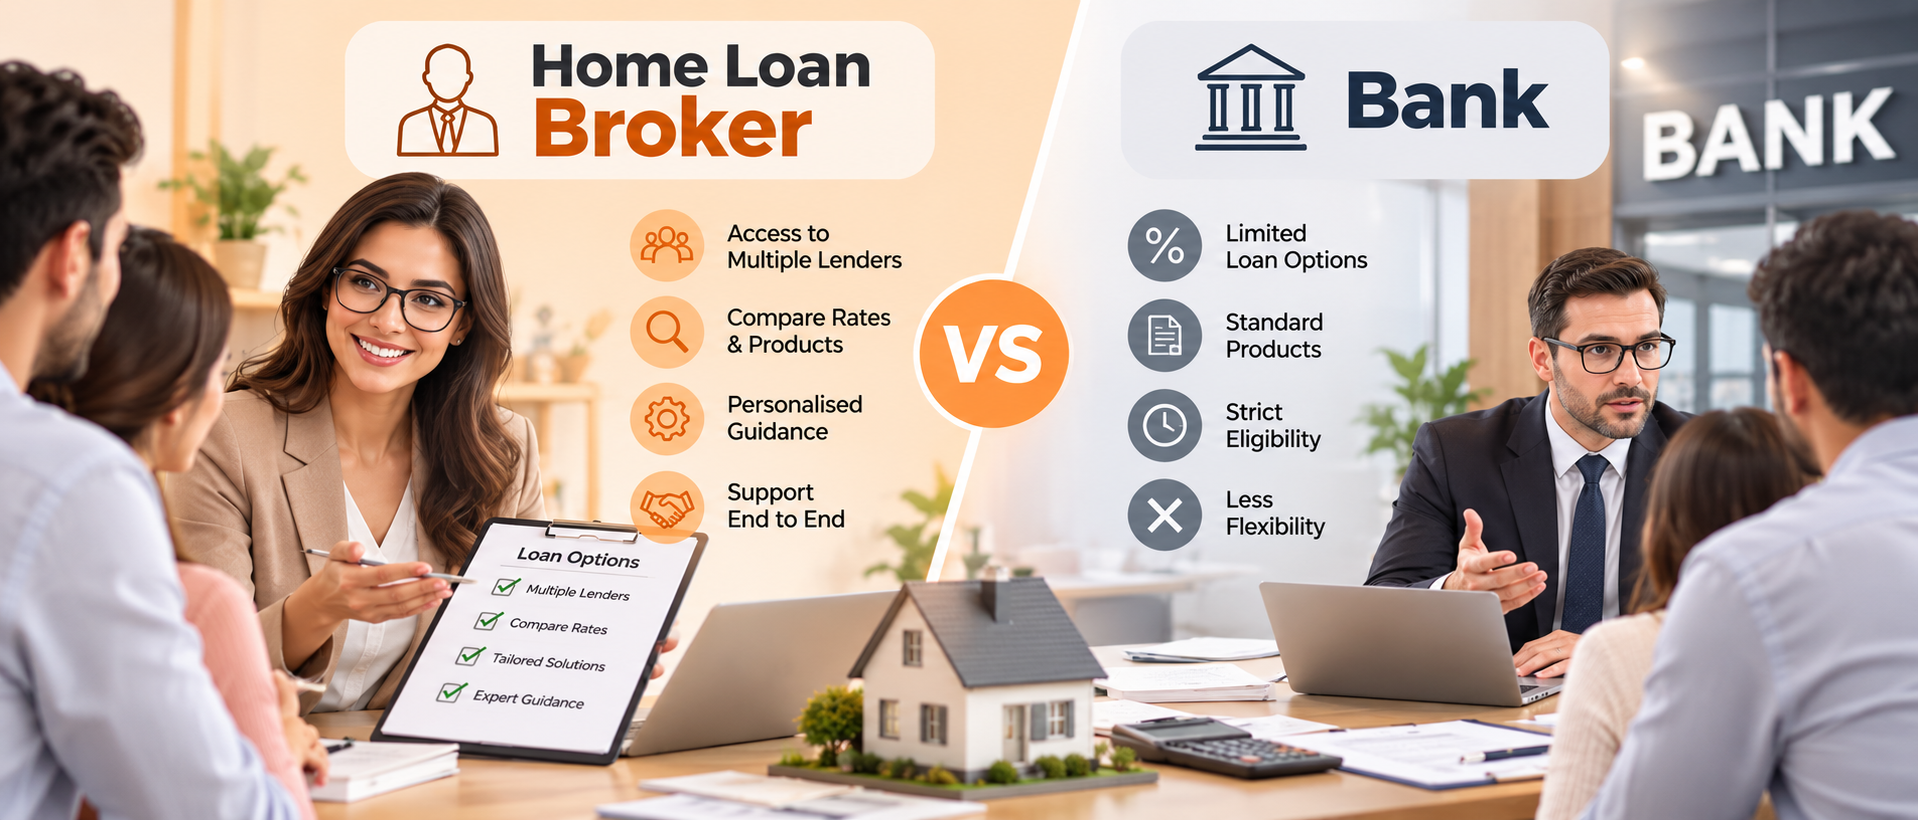
When you need a mortgage, the first decision is who to ask: your bank or a broker. The home loan broker vs bank question comes down to choice, convenience and who the adviser works for. Neither is always better, and the right pick depends on your situation.
This guide compares them side by side so you can choose with confidence. If you are new to brokers, start with what is a home loan broker.
Home Loan Broker vs Bank: Side-by-Side Comparison
| Factor | Home loan broker | Bank |
|---|---|---|
| Loan choice | Loans from many lenders on their panel | That bank's own products only |
| Who they work for | You, with a legal duty to act in your best interests | The bank |
| Comparing lenders | Part of the service | Not offered, you compare yourself |
| Paperwork | Broker prepares and lodges it | You complete it, with branch or phone help |
| Cost to you | Usually paid by the lender, ask about any fee | No broker fee |
| After settlement | Can review your loan as rates or needs change | Mainly up to you to ask |
| Access to all lenders | Most, but a few lenders deal direct only | Only itself |
Pros and Cons of Using a Home Loan Broker
Advantages
- Compares many lenders in one conversation
- Must act in your best interests
- Handles paperwork and chases the approval
- Useful for complex income, investors and self-employed
- Can review your loan again later
Things to watch
- Panels differ, so ask how many lenders they use
- Paid by commission, so ask how they are paid
- A few lenders are only available direct
- Commission may be clawed back if you refinance early
Pros and Cons of Going Directly to a Bank
Advantages
- One point of contact if you already bank there
- No broker involved in the process
- May offer existing-customer pricing or packages
- Simple if you know exactly what you want
Things to watch
- Only that bank's loans are on the table
- You compare other lenders yourself
- Staff are not obliged to find you the best deal in the market
- Policy limits can reduce your options
How Brokers and Banks Get Paid
A bank earns money from the interest on your loan. A broker is normally paid a commission by the lender once your loan settles, and often a smaller ongoing trail commission. For most standard loans you do not pay the broker separately. Some brokers charge fees for complex work, and these must be disclosed before you go ahead. We cover this in mortgage broker fees.
Because brokers are paid by lenders, it is fair to ask whether that affects advice. That is why brokers must act in your best interests when assisting with a consumer home loan, and why you should ask any broker to explain why a loan suits you.
When a Broker Makes More Sense
- You want to compare several lenders without visiting each one
- You are a first home buyer and want the process explained
- You are refinancing and want to see if switching helps
- You are an investor building a portfolio, see investment loans
- You are self-employed or have non-standard income
When Going Direct to a Bank Can Work
- You already know the exact loan you want and are happy with it
- Your bank has offered you a package or pricing you have checked against the market
- Your situation is simple and you are comfortable doing the application yourself
How to Decide
- Write down what matters most: rate, features, speed, or support.
- Get one offer from your bank and one comparison from a broker.
- Compare the rate, the fees and the features, not only the headline rate.
- Choose the option that fits your goals and that you understand fully.
For what happens once you apply, see our loan process page.
Related Guides
Compare Your Options With a Home Loan Broker
Get a free, no-obligation comparison of lenders for your situation.
Book a Free Consultation Explore Home LoansFrequently Asked Questions
Is it better to use a broker or a bank for a home loan?
Do brokers get better rates than banks?
Does it cost more to use a mortgage broker?
Can a broker access every lender?
Is a broker or a bank better for refinancing?
Can I use my bank and a broker at the same time?
This article is general information only and is not financial or credit advice. Speak to a licensed broker about your situation.